fnb100f261005a
Overview
Jeff Hunk introduces financial statement analysis for Finance 100, emphasizing that the income statement measures profit while the balance sheet describes capital structure. He explains why earnings data matters for evaluating firms, defines sales revenue as price times quantity sold, distinguishes operating revenue from passive investment income, and introduces direct/variable costs and fixed/operating expenses. Finance 100 focuses on the income statement and balance sheet, while the cash flow and retained earnings statements are reserved for Finance 230.
Key takeaways
- The income statement reports profit or loss, while the balance sheet describes capital structure; knowing those different purposes helps distinguish their line items.
- In the lesson’s notation, π means profit in microeconomics and inflation in macroeconomics, while P is reserved for price.
- Sales revenue is calculated as price times quantity sold; for a company with multiple products, total revenue is the sum of each product’s price multiplied by its quantity.
- A retailer’s markup is not automatically its profit: Best Buy’s illustrative $100 difference between a $500 sale price and $400 purchase cost must also cover operating expenses.
- Companies can retain and reinvest profit rather than distribute all of it to shareholders, using retained earnings to support growth.
- Jeff links direct costs to variable costs and cost of goods sold, and indirect costs to fixed costs and operating expenses, using restaurant spending and rent as examples.
Chapters
- Jeff Hunk opens the Monday Finance 100 session and introduces financial statements as the day’s topic.
- The class watches an introductory clip about financial statements and fundamental analysis.
- The introductory material frames financial statement knowledge as essential to evaluating financial instruments and potential returns.
- It identifies the income statement and balance sheet as statements with distinct purposes and structures.
- Recognizing flaws or discrepancies supports accurate earnings-per-share, return-on-equity, and return-on-assets calculations.
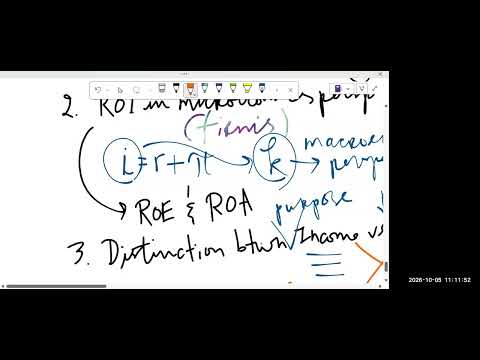
- Jeff contrasts the previous topic’s macroeconomic view of interest rates with this lesson’s firm-level, microeconomic view of investment returns.
- Return on equity and return on total assets are presented as representative measures of firm performance.
- Understanding each statement’s purpose helps prevent confusion between their line items.
- Students were expected to finish Financial Statements Intro videos 1 through 3 by October 4, after an extension from the September 15 deadline.
- Jeff directs students to his YouTube channel and the semester playlist for recordings they missed.
- The playlist includes Tuesday and Thursday sections that may be about a week ahead, offering a way to preview upcoming material.
- The four statements named are the income statement, balance sheet, cash flow statement, and retained earnings statement.
- Finance 100 concentrates on the income statement and balance sheet as the primary statements.
- Finance 230 will cover cash flow and retained earnings statements, which use data from the income statement and balance sheet.
- Jeff defines financial fundamentals as quantitative data rather than abstract or qualitative descriptions.
- Profit, also called earnings, is introduced as one important data point for analyzing a business.
- The lesson presents solid numerical evidence as the basis of fundamental analysis.
- In the microeconomics context, π denotes profit, while P is already reserved for price.
- In the macroeconomics context discussed earlier, π denotes inflation.
- The same symbol can represent different concepts depending on whether the context is microeconomics or macroeconomics.
- Jeff illustrates company performance with a hypothetical firm whose profit grows 100% annually for five years.
- He compares that firm with an industry growing about 20% during an economic boom and suggests it may outperform competitors even in a recession.
- The income statement, not the balance sheet, is identified as the source of profit data.
- The income statement’s goal is to report profit, while the balance sheet’s goal is to describe capital structure.
- The income statement is also called a profit and loss, or P&L, statement.
- A loss is explained mathematically as negative profit, while positive profit is positive profit.
- The full descriptive name used for the income statement is the income and expenses statement.
- Jeff separates the statement’s income-and-expense process from its bottom-line conclusion, profit or loss.
- He identifies sales revenue as a business’s primary source of income and investment income as a secondary source.
- Manufacturers make products and sell them; retailers buy products from manufacturers and resell them.
- Jeff defines sales revenue mathematically as price multiplied by quantity sold, or P × Q.
- In the example, Best Buy sells a Dell Model X laptop for $500 after purchasing it from Dell for $400; the $100 difference is markup, not necessarily net profit because operating expenses remain.
- A retailer selling multiple products calculates total revenue by summing each product’s price times its quantity sold.
- Jeff writes the general form as the sum of pᵢqᵢ for products i from 1 through n.
- Whether a company sells one product or thousands, revenue retains the same price-times-quantity logic.
- Jeff pauses the lesson for a planned 10-minute break at about 11:55.
- He asks students to turn on their cameras when class resumes so he can document engagement.
- After the break, Jeff checks which students have cameras turned on and requests that several turn them on.
- He takes and saves a screenshot as a record of class engagement.
- The class then resumes the financial statement lesson.
- Jeff reviews Zoom login records from September 28 and 30 and explains that reports must be sorted by students’ last names to match the course roster.
- Missing or incorrect last names require manual identification and create extra attendance-record work.
- He asks students to use only their correct first and last names, without middle names, and asks the class to flag future screen-sharing problems.
- Jeff restates that operating activity generates sales revenue through making or reselling products.
- Sales revenue remains price times quantity sold, while investment income is a separate, secondary income source.
- The recap links the income statement’s structure to the goal of measuring profit.
- Jeff explains that profit theoretically belongs to company owners, meaning shareholders in a corporation.
- Owners range from majority shareholders to very small minority shareholders, including investors with tiny fractions of total shares.
- A company may retain and reinvest profit to fund growth rather than distribute all earnings to shareholders.
- Jeff compares a worker’s after-tax paycheck to business sales revenue and household spending to business expenses.
- Food, shelter, clothing, transportation, and telecommunications are presented as household necessities.
- Money remaining after expenses becomes savings, which can then be invested.
- Jeff traces the path from earned income to savings, then uses a $500 stock purchase as an example of investing savings.
- Investment returns can be negative, with a maximum loss of 100%, while positive returns have no fixed upper limit.
- He characterizes investment income as passive in contrast with revenue generated through active business operations.
- Jeff distinguishes direct costs, which he associates with variable costs and cost of goods sold, from indirect costs, which he associates with fixed costs and operating expenses.
- A $50 steakhouse meal repeated for 10 dates totals $500 and illustrates a cost that varies with quantity; zero outings mean zero such spending.
- Rent is used as an example of a fixed expense that does not change with the number of outings; Jeff says the cost concepts will continue in the next class.
- The session closes with a question about the next in-person class and a reminder that it is planned for the following Wednesday.
Transcript excerpt
1:32 All right. Good morning, everyone. Good morning. Happy Monday. Happy Monday to everyone. Good morning. All right. Let's see who's here. Okay. first of all. Okay, so uh let me see who's here. Okay, I've got seven people so far. We have Laura, Sherish, and also Shane, um, Ral, Kadron, Max, and Enela, Ali. All right. Uh, and please, if your
2:23 if if your camera is currently off, please turn it on. Please turn it turn it on. As you uh join the room, make sure your uh camera is on. Yanelka, Elmer, Ralph, Max, Alli, please turn on your camera. All right. So, today we're moving on to financial statements. So, why is our second topic financial statements? Now, let's uh let's take a look at this video. Let's watch this video and uh see what this topic is about. Okay, take a listen. >> Okay, here.
3:15 >> Understanding the financial statements is crucial as well as fundamental to invest. >> Do you hear the audio here? You hear the audio? >> I guess something's not right, but I'm Let's see. Let me Maybe it's my volume. Okay. Okay. Let's start from the beginning. Understanding the financial statements is crucial as well as fundamental to investing. A sound knowledge and firm understanding of business finance is the first step in fundamental analysis of
4:02 financial instruments in terms of their return on investment from microeconomic or the firm's perspective. It is therefore critical to be able to distinguish between the different purposes of the income statement and the balance sheet. This ability to discern these two statements will enable you to easily tell why certain line items serve specifically one statement but not the other and give you a good structural understanding of these statements. Upon successful completion of this
This is the start of the transcript. Save this video free for the whole transcript, searchable and time-coded.
In this course
Related notes
Summary, takeaways, and chapters were generated by AI from the video's transcript and may contain errors. The video belongs to its creator, Jeff Hunk.