15. Projections onto Subspaces
 Watch on YouTube →
Overview
The lecture derives orthogonal projection first onto a line and then onto the column space of a matrix, showing that the nearest point is characterized by an error perpendicular to the subspace. It develops the normal equations A^T A x̂ = A^T b and the projection matrix A(A^T A)^-1A^T, then applies the setup to fitting a line to three data points that cannot all lie on one line.
Key takeaways
- The closest point on a line through a nonzero vector a is a(a^T b)/(a^T a), obtained by requiring the residual b - P to be perpendicular to a.
- An orthogonal projection matrix is symmetric and idempotent: P^T = P and P^2 = P, since projecting twice has the same result as projecting once.
- For a full-column-rank matrix A, the least-squares coefficients satisfy A^T A x̂ = A^T b and equal (A^T A)^-1 A^T b.
- The residual e = b - A x̂ lies in N(A^T), which is orthogonal to Col(A); this algebraic condition is exactly the geometric requirement for the nearest-point projection.
- The projection onto Col(A) is A(A^T A)^-1A^T, and A itself cannot generally be inverted or canceled because it is rectangular.
- Fitting b = C + Dt to (1,1), (2,2), and (3,2) creates a 3-equation, 2-unknown inconsistent system; least squares finds the line minimizing the residual through the normal equations.
Chapters
0:00
Deriving the Projection of b onto a Line Through a
- The closest point P on the line through a has the form P = ax, so the unknown is the scalar coefficient x.
- The error e = b - ax must be perpendicular to a, giving a^T(b - ax) = 0.
- Solving yields x = (a^T b)/(a^T a) and P = a(a^T b)/(a^T a), assuming a is nonzero.
5:34
The Rank-One Projection Matrix and Its Two Defining Properties
- Writing P as a matrix acting on b gives the projection matrix aa^T/(a^T a).
- The matrix has rank one and column space equal to the line spanned by a.
- It is symmetric, P^T = P, and idempotent, P^2 = P, because projecting a point already on the line leaves it unchanged.
- Doubling b doubles its projection, while scaling a does not change the line or the projection.
15:20
Why Projections Solve Inconsistent Systems Ax = b
- When b is outside the column space of A, the equation Ax = b has no solution.
- Instead, choose the closest vector in Col(A), the projection P of b, and solve Ax̂ = P.
- The least-squares solution x̂ gives the coefficients of the best approximation to b using the columns of A.
19:42
Representing a Plane with the Columns of A
- In the three-dimensional example, independent vectors a₁ and a₂ form a basis for a plane.
- Putting a₁ and a₂ into the columns of A makes that plane equal to Col(A); the same setup extends to n columns.
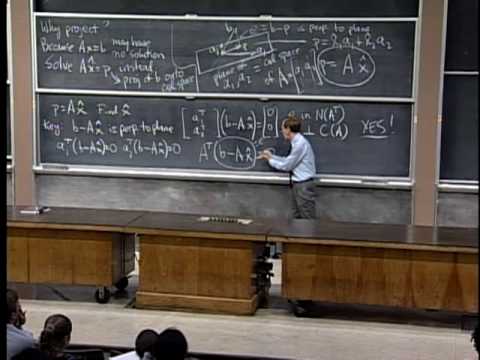
- The projected point is P = A x̂, and the residual e = b - A x̂ is perpendicular to the plane.
24:28
Perpendicular Residuals Produce the Normal Equations
- For a plane spanned by a₁ and a₂, the residual must satisfy a₁^T e = 0 and a₂^T e = 0.
- Combining those conditions gives A^T(b - A x̂) = 0.
- The equation is equivalent to A^T A x̂ = A^T b, with one equation for each column coefficient.
28:00
Connecting the Residual to the Four Fundamental Subspaces
- The condition A^T e = 0 places the residual e in the null space of A^T.
- The null space of A^T is orthogonal to Col(A), matching the geometric requirement that the error be perpendicular to the projected subspace.
- The line-projection equation is the one-column special case of the same normal-equation framework.
32:27
Least-Squares Coefficients and the General Projection Formula
- When A has linearly independent columns, A^T A is invertible and x̂ = (A^T A)^-1 A^T b.
- Substituting x̂ into P = A x̂ gives P = A(A^T A)^-1A^T b.
- The projection matrix is therefore A(A^T A)^-1A^T, extending aa^T/(a^T a) from a line to a higher-dimensional column space.
35:49
Why the Rectangular Matrix A Cannot Be Inverted
- A is generally rectangular when there are more equations than unknowns, so A has no ordinary inverse and the factors in (A^T A)^-1 cannot be split apart.
- If A is square and invertible, Col(A) is all of R^n, so projection onto that space is the identity matrix.
- The higher-dimensional projection matrix remains symmetric and idempotent, as confirmed by transposing it and simplifying its square.
42:00
Setting Up a Least-Squares Line Fit for Three Data Points
- The example fits b = C + Dt to the points (1,1), (2,2), and (3,2), which do not lie on a single line.
- The desired equations are C + D = 1, C + 2D = 2, and C + 3D = 2, giving A = [[1,1],[1,2],[1,3]], x = [C,D]^T, and b = [1,2,2]^T.
- Because the system has three equations and two unknowns, it is inconsistent; the next step is to solve A^T A x̂ = A^T b for the best-fit line.
Summary, takeaways, and chapters were generated by AI from the video's transcript and may contain errors. The video belongs to its creator, MIT OpenCourseWare.