GERO 200 f2026 Module 3 Generations in the US Video 2026 09 06 1
 Watch on YouTube →
Overview
John Walsh connects aging and generational change in the United States to economic pressures and business opportunities, including retirement spending, housing affordability, fertility, and generationally tailored marketing. He highlights that only about 22% of California households could afford a median-priced home in 2026, contrasts US family support with Sweden's shared 480 days of parental leave, and explains how cohort traits and wealth transfers can inform business planning.
Key takeaways
- An aging population increases healthcare and retirement-system demands while shifting Baby Boomers from 401(k) contributions to asset withdrawals, creating economic effects for younger generations.
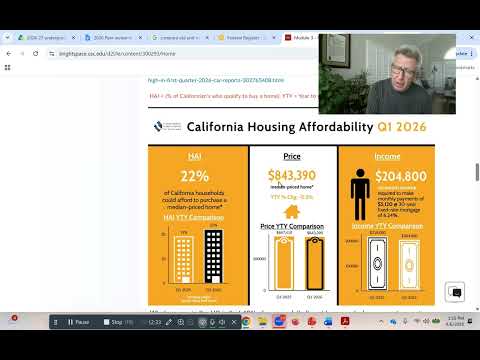
- Walsh cites a California median home price near $850,000 in 2026 and estimates that only about 22% of households could afford a median-priced home.
- The US fertility rate is below the replacement benchmark of approximately 2.1 children per woman, while the costs of housing and raising children can make family formation harder for younger adults.
- Sweden's 480 days of shared, tax-funded parental leave and South Korean corporate payments reported at up to $72,000 per child illustrate approaches to supporting families that differ from the US model.
- Businesses can use cohort differences to tailor products and outreach, such as television marketing to older audiences and social-media influencer campaigns to Gen Z consumers.
- Baby Boomer home equity and retirement wealth may flow to younger generations through spending and inheritance, making generational wealth transfer relevant to business planning.
Chapters
0:00
Course Logistics and the Economic Burden of an Aging Population
- Students should use the course announcements, syllabus, and module pages to track quizzes, discussions, and writing-assignment deadlines.
- John Walsh directs course-administration questions to Julia by email because she manages the course support system.
- Longer lifespans can bring increased frailty, doctor visits, and healthcare costs, while Social Security and Medicare place funding pressure on younger generations.
- Retirees shift from contributing to 401(k) investments toward withdrawing assets, a change that may affect retirement planning and the broader economy.
5:27
US Generations as Business Markets and the Affordability Debate
- The cohort framework includes the Greatest Generation, Silent Generation, Baby Boomers, Generation X, Millennials, Generation Z, and Generation Alpha.
- Understanding each generation's experiences, preferences, and spending can guide business plans, such as multigenerational housing, real estate development, and reverse mortgages.
- Walsh frames the class discussion around whether younger adults can afford the American Dream of a stable job, homeownership, and family life.
- He describes younger adults facing difficult job searches, underpaid entry-level work, and higher housing costs than earlier generations encountered.
9:00
Home Prices, Child-Raising Costs, and Declining US Fertility
- Walsh contrasts his 1989 first condominium purchase at about $220,000 with current barriers to homeownership for younger cohorts.
- He cites a California median home price approaching $850,000 and estimates that about 22% of households could afford a median-priced home in 2026.
- The US fertility rate is below the approximate replacement level of 2.1 children per woman, which raises concerns about the future workforce and support for Social Security and Medicare.
- At a baseline household income of $68,400, the cited national estimate requires about $23,000 more annual income to raise one child; Walsh says Orange County costs are higher.
15:30
Family Benefits in Sweden and Corporate Incentives in South Korea
- Walsh says the United States invests less in public family benefits than wealthy market-based peers, leaving families to shoulder more childcare costs.
- A Swedish parent group describes 480 days of shared parental leave funded by government taxes.
- The lecture cites family-benefit spending of about 3.8% of income in countries such as Iceland, Sweden, and Denmark, compared with roughly 2.3% across wealthy market-based countries.
- South Korean companies offer substantial childbirth incentives, including a reported $72,000 payment per child, while a proposed US $5,000 benefit is described as comparatively small.
21:20
How Cohort Traits Shape Marketing and Business Plans
- Generational analysis links social and political experiences to life priorities, spending habits, and needed public infrastructure.
- Walsh contrasts Baby Boomer priorities around job security and homeownership with Millennials' emphasis on work-life balance and flexibility, and a renewed focus on stability among younger adults.
- Marketing channels differ by cohort: older audiences may see television ads, while younger consumers are reached through phones, apps, and social platforms.
- Gen Z surfers with Instagram and YouTube audiences illustrate influencer marketing for products such as energy drinks, surf trunks, and rash guards.
28:50
Boomer Wealth Transfers and Unequal Fertility Trends
- Walsh describes Baby Boomers as holding substantial accumulated wealth through retirement accounts and home equity, with assets expected to be spent down or transferred to younger generations.
- Deloitte is cited as an example of a major firm studying demographic change and generational consumer behavior for business planning.
- Housing affordability remains low: Walsh compares a cited 15% figure for 2025 with about 22% in 2026, while cautioning that the first-home income estimate of $300,000 to $350,000 may be understated.
- A fertility comparison across 2008 to 2012, 2013 to 2017, and 2018 to 2022 shows declining births among many income groups, while wealthier households can more readily afford childcare.
Summary, takeaways, and chapters were generated by AI from the video's transcript and may contain errors. The video belongs to its creator, John Walsh.