Applied Probability - F26 - Lecture 6
 Watch on YouTube →
Overview
Arash Amini builds the Lebesgue integral from measurable simple functions, extending it to nonnegative functions by a supremum and to integrable signed functions through positive and negative parts. He develops the Monotone Convergence Theorem, Fatou’s lemma, and the Dominated Convergence Theorem, then applies the framework to expectation and the Law of the Unconscious Statistician.
Key takeaways
- The Lebesgue integral is built by defining values on simple functions and taking suprema over simple functions below any nonnegative measurable function.
- If nonnegative measurable functions increase pointwise to a limit, their integrals increase to the integral of that limit; this also permits exchanging integrals with sums of nonnegative functions.
- Pointwise convergence alone does not guarantee convergence of integrals: shrinking spikes and intervals moving to infinity both have constant integral while converging pointwise to zero.
- An integrable dominating function makes pointwise convergence sufficient for L¹ convergence, which in turn guarantees convergence of the integrals.
- The Law of the Unconscious Statistician computes E[g(X)] by integrating g against the distribution P_X, avoiding the need to derive the distribution of g(X).
Chapters
0:00
Simple Functions Define the Integral and Expectation
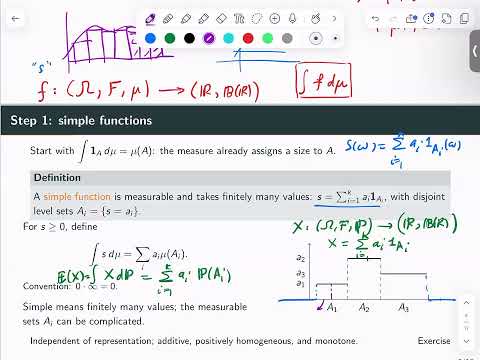
- For a simple function s = sum_i a_i 1_{A_i} on disjoint measurable sets, define its integral as sum_i a_i μ(A_i).
- A simple random variable taking finitely many values has expectation equal to the sum of each value times the probability of its event.
- The measure μ determines the weights: they may be set sizes under Lebesgue measure or event probabilities under a probability measure.
6:36
Simple-Function Integrals Are Linear and Monotone
- Different representations of a simple function give the same integral; splitting a measurable set into pieces preserves the total.
- Common refinements of the level sets show that the integral of f + g equals the sum of the integrals for simple functions.
- Scaling a simple function scales its integral, and pointwise s₁ ≤ s₂ implies ∫s₁ dμ ≤ ∫s₂ dμ.
12:49
Extend the Integral to Nonnegative Measurable Functions
- For measurable f ≥ 0, define ∫f dμ as the supremum of ∫s dμ over all nonnegative simple functions s ≤ f.
- The resulting integral is always defined, although its value may be +∞.
- The supremum construction preserves monotonicity and agrees with the earlier definition when f is simple.
16:34
Approximate Measurable Functions from Below
- Every nonnegative measurable f is the pointwise increasing limit of nonnegative simple functions sₙ.
- A construction uses truncation at increasing bounds and increasingly fine dyadic steps to approximate f from below.
- The approximation lemma supplies the simple-function sequences used to extend integral identities to general functions.
21:55
Monotone Convergence and Its Integral Consequences
- The Monotone Convergence Theorem states that if 0 ≤ fₙ ↑ f pointwise, then ∫fₙ dμ ↑ ∫f dμ, including when the limit is infinite.
- Together with simple-function approximation, the theorem extends additivity from simple functions to all nonnegative measurable functions.
- Applying it to partial sums gives ∫(sumₙ fₙ) dμ = sumₙ ∫fₙ dμ for nonnegative measurable functions, without requiring finite values.
30:43
Fatou’s Lemma from Increasing Tail Infima
- For nonnegative measurable fₙ, Fatou’s lemma gives ∫liminfₙ fₙ dμ ≤ liminfₙ ∫fₙ dμ.
- Define gₘ = inf_{n≥m} fₙ; these tail infima increase pointwise to liminf fₙ.
- Monotone Convergence applied to gₘ, together with gₘ ≤ fₙ for n ≥ m, yields the inequality.
35:32
Two Failures of Integral Convergence Under Pointwise Limits
- On (0,1), fₙ(x) = n·1_{(0,1/n)}(x) has integral 1 for every n but converges pointwise to 0.
- On the real line, indicators of intervals (n,n+1) also have integral 1 while converging pointwise to 0 as their mass escapes to infinity.
- These examples explain why Fatou’s inequality may be strict and why pointwise convergence alone does not preserve integrals.
40:28
Positive and Negative Parts Define Signed Integrals
- Write a measurable real-valued f as f⁺ − f⁻, where f⁺ = max(f,0) and f⁻ = max(−f,0).
- The identity |f| = f⁺ + f⁻ shows that ∫|f| dμ < ∞ guarantees both parts have finite integrals.
- Such functions are integrable, or in L¹(μ); defining the signed integral as ∫f⁺ dμ − ∫f⁻ dμ avoids the undefined expression ∞ − ∞.
48:26
Dominated Convergence Theorem Gives L¹ Convergence
- If measurable fₙ converge pointwise to f and |fₙ| ≤ g for an integrable g, then f is integrable and ∫|fₙ − f| dμ → 0.
- The bound |f| ≤ g follows by taking pointwise limits, so the limit function is also in L¹.
- Set hₙ = |fₙ − f|; then 0 ≤ hₙ ≤ 2g and hₙ → 0, allowing Fatou’s lemma applied to 2g − hₙ to establish convergence of the integrals.
55:40
Why Domination Matters for Pointwise Convergence
- The integrable dominating function prevents the concentration and escape-to-infinity behaviors illustrated by the earlier counterexamples.
- Dominated convergence requires pointwise convergence and an integrable bound, not continuity or uniform convergence.
- The result implies ∫fₙ dμ → ∫f dμ because |∫fₙ dμ − ∫f dμ| ≤ ∫|fₙ − f| dμ.
59:16
Almost-Everywhere Convergence and a Proof Blueprint
- The convergence theorems also apply when their hypotheses hold almost everywhere, meaning outside a set of measure zero.
- Changing a function on a measurable null set does not change its Lebesgue integral; on the real line, countable sets have Lebesgue measure zero.
- For identities such as Fubini’s and Tonelli’s theorems, a reusable strategy is to prove the claim for indicators, then simple functions, then nonnegative functions via monotone convergence.
1:02:47
Expectation Is Integration Against the Probability Measure
- For a random variable X on a probability space, define E[X] as the Lebesgue integral ∫X dP when X is integrable.
- For a finite-valued X, this reduces to the familiar weighted average of its values by event probabilities.
- The distribution P_X is the pushforward of P under X, moving the measure from the original sample space to the variable’s value space.
1:05:12
Law of the Unconscious Statistician Changes the Integration Space
- For a measurable function g, the key identity is ∫g(X) dP = ∫g(x) dP_X(x), whenever the integrals are defined.
- To compute E[X²], integrate x² against the distribution of X rather than first deriving the distribution of the new variable X².
- The identity replaces integration over the original sample space with integration over the value space using the pushforward distribution.
1:10:16
Prove the Pushforward Integral Identity from Indicators
- For a measurable set B, the indicator identity follows from ∫1_B(X) dP = P(X ∈ B) = P_X(B) = ∫1_B dP_X.
- Linearity extends the identity from indicators to simple functions, and Monotone Convergence extends it to nonnegative measurable functions.
- Splitting into positive and negative parts extends the result to integrable signed functions, completing the Law of the Unconscious Statistician.
Summary, takeaways, and chapters were generated by AI from the video's transcript and may contain errors. The video belongs to its creator, ARASH AMINI.