Applied Probability - F26 - Lecture 5
 Watch on YouTube →
Overview
Arash Amini connects measurable maps, push-forward laws, and product sigma algebras to show how probability distributions extend from single random variables to random vectors and stochastic processes. He derives inverse transform sampling from a Uniform(0,1) variable, then introduces the Lebesgue integral by defining it first for indicator functions and simple functions.
Key takeaways
- For any real-valued CDF F and U distributed uniformly on (0,1), the generalized inverse F⁻¹(U) has CDF F, including when F is discontinuous.
- A random vector is measurable into a product space exactly when each of its coordinate random variables is measurable.
- The joint law of (X₁, X₂) is determined by probabilities P(X₁ ∈ B₁, X₂ ∈ B₂) on measurable rectangles; marginal laws alone do not determine joint behavior.
- For a stochastic process indexed by T, the cylinder sigma algebra is generated by evaluations at individual times, and its law is determined by finite-dimensional distributions.
- Lebesgue integration assigns μ(A) to the indicator 1_A and Σ aᵢμ(Aᵢ) to a simple function Σ aᵢ1_Aᵢ, forming the basis for extending integration to broader classes of measurable functions.
Chapters
0:00
Pullbacks, Initial Sigma Algebras, and Information in Random Variables
- Pulling a target sigma algebra back through a map means taking preimages of its measurable sets.
- The pullback sigma algebra coincides with the smallest, or initial, sigma algebra that makes the map measurable.
- The sigma algebra generated by random variables represents the information they contain; measure-theory symbols such as sigma and mu do not mean standard deviation and mean.
5:45
Push-Forward Measures Define a Random Variable’s Law
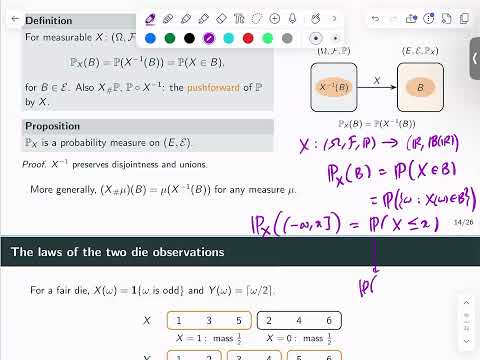
- A measurable map pushes a probability measure on its source space to a probability measure on its target space.
- For a real-valued random variable X, its law assigns a Borel set B the probability P(X ∈ B).
- The law is determined by its CDF, F(x) = P(X ≤ x), because half-lines generate the Borel sigma algebra on R.
10:00
Constructing Any Real-Valued Law from Uniform(0,1)
- A CDF is nondecreasing and right-continuous, with limits 0 at negative infinity and 1 at positive infinity.
- Define the generalized inverse or quantile function by F⁻¹(u) = inf{x : F(x) ≥ u} for 0 < u < 1.
- If U is Uniform(0,1), then F⁻¹(U) has CDF F; this inverse transform works even when F has jumps or flat sections.
16:40
Quantile Function for a Point Mass Plus a Uniform Component
- The example CDF places probability 1/2 at 0 and spreads the remaining probability uniformly over [1,2].
- For 0 < u ≤ 1/2, the generalized inverse returns 0; for 1/2 < u < 1, it returns 2u.
- The example shows how a CDF jump creates a flat section of the quantile function, while a flat CDF section corresponds to a quantile jump.
21:00
Why the Generalized Inverse Produces the Desired CDF
- The CDF limits ensure the set {x : F(x) ≥ u} is nonempty for every u in (0,1), and right-continuity ensures its infimum is attained.
- Monotonicity gives the event equivalence {F⁻¹(U) ≤ x} = {U ≤ F(x)}.
- Because U is uniform, P(U ≤ F(x)) = F(x), establishing the target CDF and the measurability of F⁻¹(U).
26:00
Joint Laws Extend Push-Forward Distributions to Random Vectors
- Individual random variables X₁ and X₂ have marginal laws obtained by pushing the original probability measure through each coordinate map.
- A joint law requires a measurable structure on the product space E₁ × E₂ so probabilities can be assigned to joint events.
- The pair (X₁, X₂) is a map from the original probability space into E₁ × E₂, and its push-forward is the joint distribution.
30:40
Product Sigma Algebras from Coordinate Strips and Rectangles
- The product sigma algebra is the smallest sigma algebra on E₁ × E₂ that makes both coordinate projections measurable.
- Preimages under the projections are coordinate strips, such as B₁ × E₂ and E₁ × B₂.
- Intersections of these strips give measurable rectangles B₁ × B₂, which generate the product sigma algebra and form a pi-system.
35:00
Product Sigma Fields Are Not Cartesian Products of Sigma Fields
- The product sigma field contains subsets of E₁ × E₂, whereas the Cartesian product of two sigma fields consists of pairs of sets.
- For a family of spaces, the product sigma algebra is the smallest sigma algebra making every coordinate projection measurable.
- This construction depends on the spaces and their sigma fields, not on whether particular random variables share an original domain.
44:20
A Random Vector Is Measurable Exactly When Its Coordinates Are
- A map into a product space is measurable with respect to the product sigma algebra if and only if each coordinate map is measurable.
- The result follows by taking preimages of coordinate-projection sets and checking the corresponding coordinate preimages.
- On Rᵈ, the product of d Borel sigma algebras equals the Borel sigma algebra generated by open sets in Rᵈ.
47:00
Pulling Back the Product Sigma Algebra Captures Generated Information
- For a measurable random vector X = (X₁, …, Xₙ), pulling back the product sigma algebra gives the sigma algebra generated by its coordinates.
- This pullback is the smallest sigma algebra on the original space that makes every Xᵢ measurable.
- The identity links the product-space construction to the earlier idea of sigma algebras generated by random variables.
50:00
Joint Probabilities on Rectangles Distinguish Dependence from Marginals
- The joint law assigns B₁ × B₂ the probability P(X₁ ∈ B₁ and X₂ ∈ B₂).
- Measurable rectangles determine the joint measure, whereas probabilities on coordinate strips alone provide only the marginal distributions.
- Although rectangles generate the product sigma field, more complex sets, such as a circle in R², are also measurable.
54:00
Cylinder Sigma Algebras Represent Laws of Stochastic Processes
- A product indexed by an uncountable set T can be viewed as the function space Rᵀ, consisting of functions from T to R.
- Coordinate projections become evaluation maps f ↦ f(t); the sigma algebra they generate is called the cylinder sigma algebra.
- Cylinder sets constrain a function at finitely many times, and the resulting process law is determined by finite-dimensional distributions.
- The cylinder sigma algebra need not include every event of interest; the event that a sample function is continuous may not belong to it.
1:02:00
Recap: Product Sigma Algebras Connect Random Vectors and Processes
- The product sigma algebra can be described through coordinate projections, coordinate strips, or measurable rectangles.
- Pushing the original probability measure through a random vector or process gives its joint or path law.
- These constructions extend the law of a single random variable to collections of variables indexed by coordinates or time.
1:05:30
Lebesgue Integration Starts with Indicators and Simple Functions
- Unlike the Riemann approach of subdividing the domain, the Lebesgue approach organizes the range of a function and uses measure on its level sets.
- For a measurable set A, define the integral of its indicator 1_A as μ(A); under Lebesgue measure, an interval indicator integrates to the interval’s length.
- For a simple function s = Σ aᵢ1_Aᵢ on disjoint measurable sets, define its integral as Σ aᵢμ(Aᵢ).
- The construction begins with indicators, extends by linearity to simple functions, and then by limits to measurable nonnegative functions.
Summary, takeaways, and chapters were generated by AI from the video's transcript and may contain errors. The video belongs to its creator, ARASH AMINI.